Vike Insurance
Specialty Insurance

Complex Risks Deserve Specialist Cover

For businesses and individuals with unique or high-value risks, our specialty insurance portfolio covers marine cargo, aviation, cyber liability, bonds, and more.

Marine + aviationConstruction + engineeringBonds + guaranteesCustom underwriting
Specialty Insurance
Custom
Underwriting
Specialist
Broker Team
30+
Years Experience
10+
Underwriter Partners
98%
Claims Paid 2024
4.4
Google Rating

What We Cover

5 types of specialty insurance cover. Each one has its own page with the full policy detail, pricing and claims process.

  • Marine / Cargo Insurance

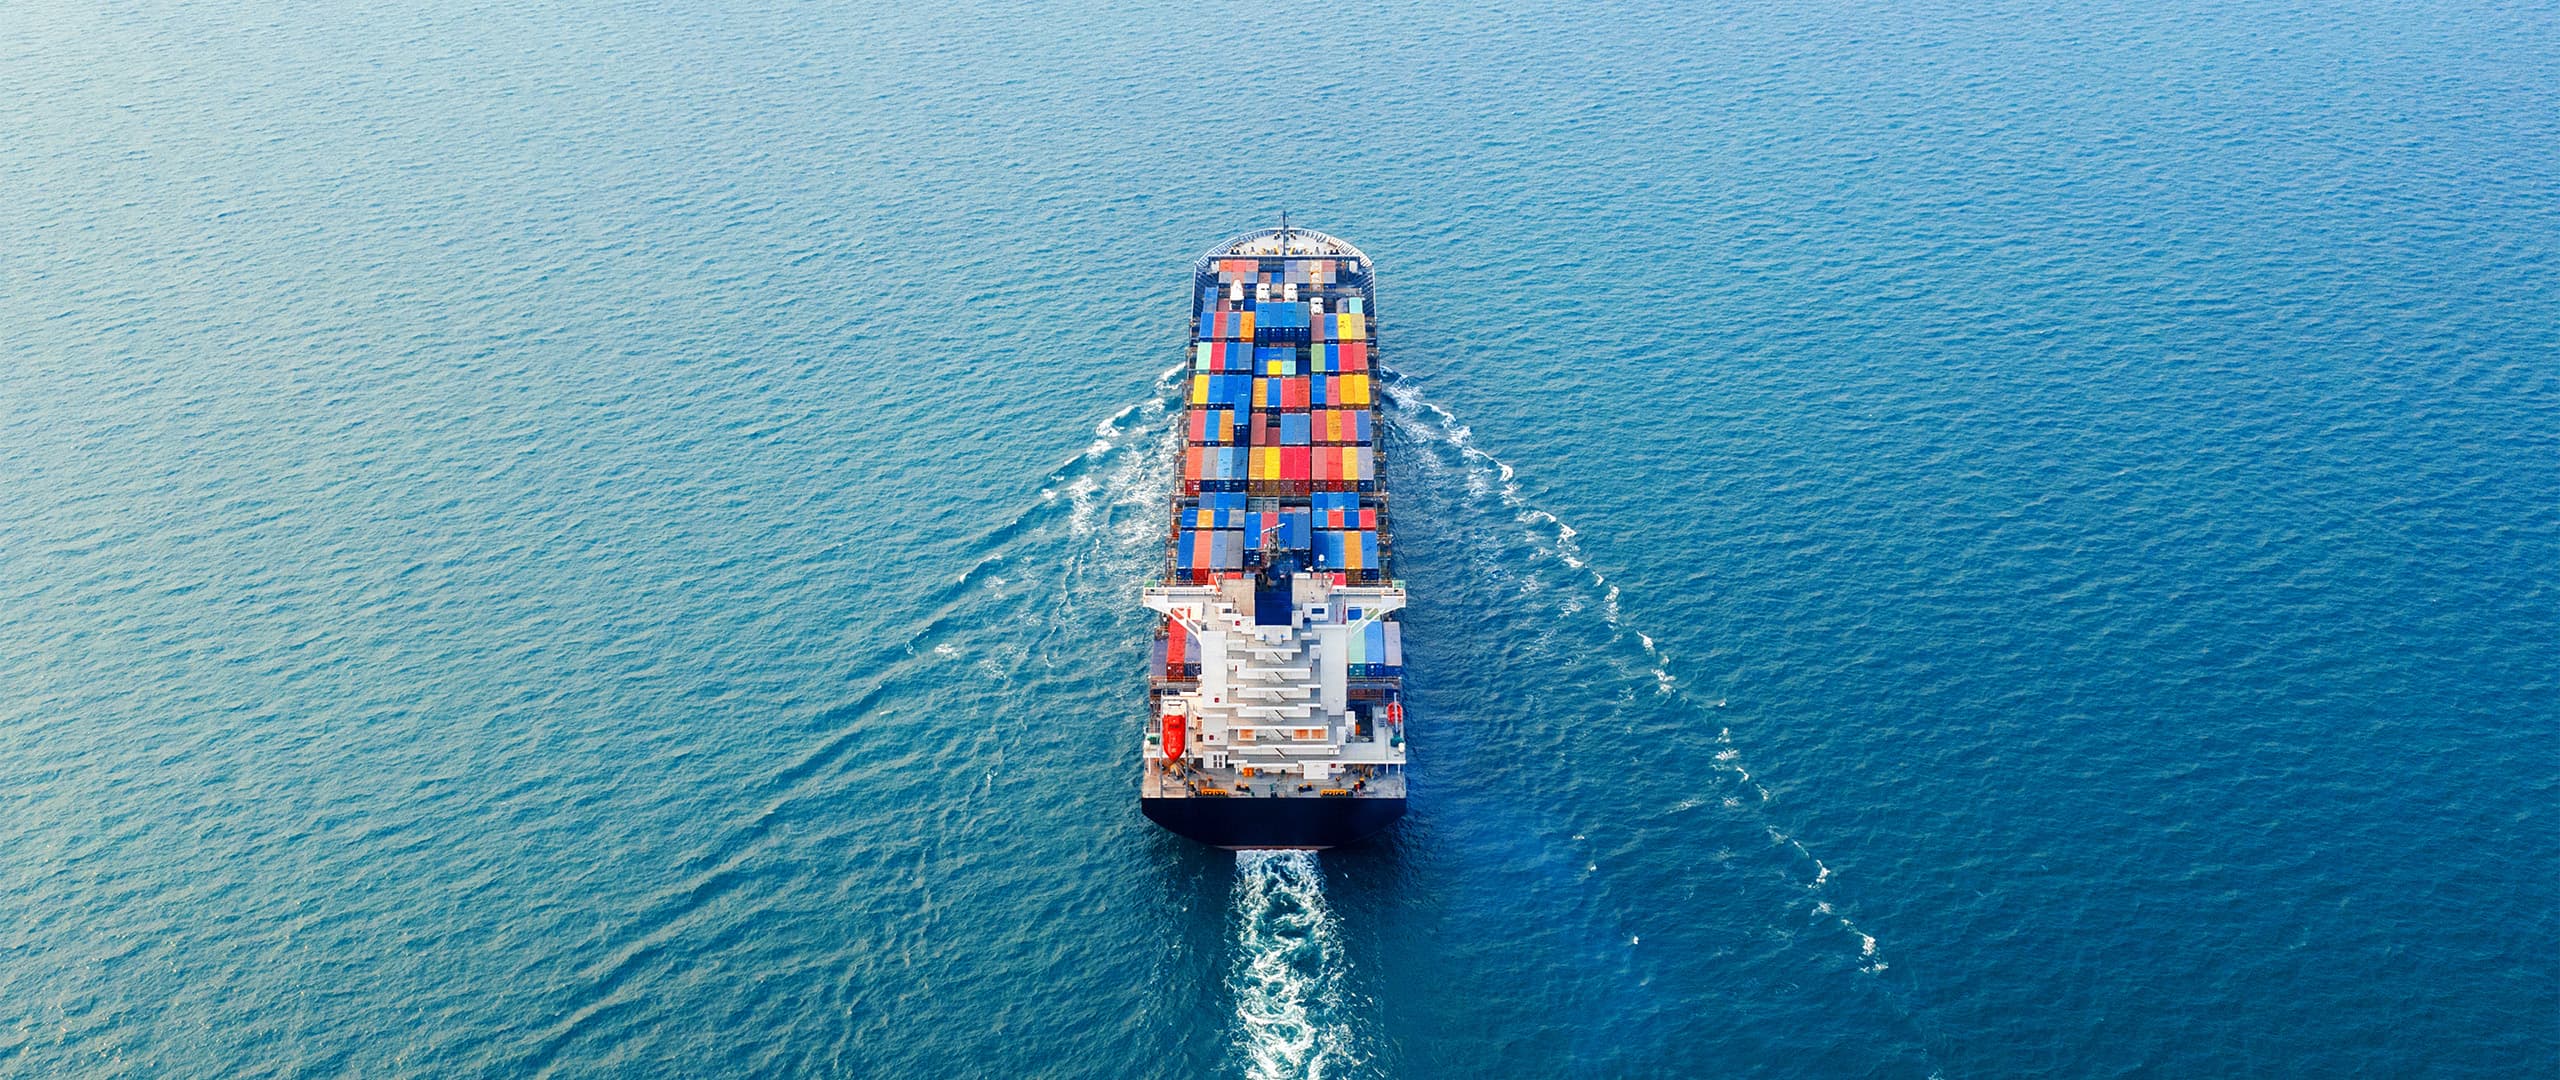
    Covers goods in international and domestic transit by sea, air, or road: import, export, and inland movement on Institute Cargo Clauses.

    What it covers

    • Loss or damage to cargo during international and domestic transit
    • Cover under Institute Cargo Clauses A (all risks), B (named perils), or C (major casualties only)
    • Marine, air, road, and rail transit segments
    More about Marine / Cargo Insurance

    Marine cargo insurance covers goods being moved internationally and domestically: predominantly by sea, but also by air, road, and rail. The wording is built on the Institute Cargo Clauses (ICC A, B, and C), an internationally standardised framework that determines what perils are covered. Cargo insurance is distinct from the carrier's own liability, which is severely limited by international convention, for any meaningful import or export value, the cargo owner needs their own cover.

    Also covers

    • Loading and unloading at ports, airports, and warehouses
    • General Average and salvage charges

    Who it's for

    • Importers receiving cargo through Mombasa, Naivasha, or JKIA
    • Exporters shipping out of Kenya: tea, coffee, horticulture, manufactured goods
    • Freight forwarders and clearing agents arranging cover on behalf of clients
  • Aviation Insurance

    Hull and liability cover for aircraft operators, owners, charter companies, flying schools, and aviation service providers across the region.

    What it covers

    • Hull: physical damage to the aircraft (in flight, taxi, and ground)
    • Passenger legal liability: injury or death of passengers
    • Third-party legal liability: injury or damage to people and property on the ground
    More about Aviation Insurance

    Aviation insurance is a specialist class placed almost entirely through reinsurance markets in London, with limited local capacity. Cover includes hull (physical damage to the aircraft), passenger and third-party liability, and ground risks. Each of which is rated and underwritten distinctly. Kenya has a substantial general aviation sector. Charter operators, flying schools, agricultural aviation, NGO and tourism operators: and a small but growing commercial fleet.

    Also covers

    • War, hijacking, and political risk perils (separate cover)
    • Hangar-keepers' legal liability for FBOs and maintenance organisations

    Who it's for

    • Charter operators (commercial and corporate)
    • Flying schools and training organisations
    • Tour operators with their own aircraft for safari and coastal routes
  • Bonds (Bid, Performance & Advance Payment)

    Financial-guarantee bonds for government tenders, construction contracts, supply agreements, and customs obligations.

    What it covers

    • Bid bonds: guarantees the bidder will sign the contract if awarded
    • Performance bonds: guarantees the contractor will perform per the contract
    • Advance payment bonds: guarantees repayment of advances if the contract fails
    More about Bonds (Bid, Performance & Advance Payment)

    Insurance bonds are financial guarantees provided by an insurer to a beneficiary (typically a public-sector buyer or contracting authority) on behalf of a principal (a contractor or supplier). If the principal fails to meet the underlying obligation, bidding, performing, repaying an advance, or paying customs. The insurer pays the beneficiary up to the bond limit, then pursues recovery from the principal. Bonds free up the contractor's working capital that would otherwise be tied up in cash deposits or bank guarantees.

    Also covers

    • Retention bonds: releases retention monies in exchange for a bond guarantee
    • Customs bonds: guarantees payment of duties and taxes for KRA

    Who it's for

    • Contractors bidding for public-sector and parastatal tenders
    • Suppliers under government and corporate supply agreements
    • Importers needing KRA customs and excise bonds
  • Political Violence & Terrorism (PVT) Insurance

    Covers business assets and operations against loss from riot, strike, terrorism, sabotage, civil commotion, and political violence in Kenya and the region.

    What it covers

    • Acts of terrorism: bombing, armed attack, sabotage
    • Acts of sabotage by political or ideological actors
    • Riot, strike, and civil commotion (when included as a peril)
    More about Political Violence & Terrorism (PVT) Insurance

    Political Violence and Terrorism (PVT) is a specialist class covering loss to business assets and operations arising from acts of terrorism, sabotage, riot, strike, civil commotion, insurrection, and similar political-violence events. Standard Fire and IAR policies cover only the lower end of this spectrum (riot and strike are usually included; full terrorism and sabotage are explicitly excluded). PVT plugs the gap that has become economically critical in Kenya since 2010.

    Also covers

    • Insurrection, rebellion, and revolution (per policy wording)
    • Damage to buildings, plant, stock, and contents

    Who it's for

    • Businesses with offices or operations in Nairobi CBD, Westlands, Upperhill
    • Banks, hotels, malls, and other public-access venues
    • Diplomatic-adjacent and high-profile commercial properties
  • Cyber Liability Insurance

    Protects your business against the financial and legal fallout of data breaches, ransomware attacks, business email compromise, and cyber-related liability.

    What it covers

    • Forensic investigation and incident response costs
    • Ransomware payment and negotiation (subject to legal and policy constraints)
    • Data and system restoration costs
    More about Cyber Liability Insurance

    Cyber Liability is the dedicated cover for the modern threat profile most Kenyan businesses now face: ransomware, business email compromise (BEC), data breaches, social engineering fraud, and the legal liability that follows when customer or employee data is exposed. Kenya's Data Protection Act, 2019 imposes specific obligations on data controllers, including notification of breaches and potential ODPC penalties, and cyber liability is the product that responds to both the operational fallout and the regulatory consequences.

    Also covers

    • Business interruption following a cyber event
    • Notification costs to affected customers and employees

    Who it's for

    • Tech companies, SaaS providers, and IT consultancies
    • Financial institutions: banks, saccos, microfinance, fintechs
    • E-commerce and online retailers

Why Choose Vike?

Specialist underwriters for complex risks

Tailored policy wording reviewed by experts

Risk management advisory included

Lloyd's of London and local market access

Quotes from Kenya's leading underwriters

First Assurance
CIC General
Jubilee Allianz
Heritage Insurance
Britam
ICEA Lion
Madison Insurance
Monarch
Definite Assurance
Old Mutual
Pioneer General Insurance

Specialty Insurance FAQs

What is the difference between ICC A, B, and C?
ICC A is broadest: 'all risks' subject only to specific exclusions. ICC B covers a defined list of named perils. ICC C is the narrowest. Major casualty events only (sinking, fire, collision). For commercial cargo, ICC A is now the market default and the only sensible choice for most importers.
Is aviation hull cover available for private Kenyan operators?
Yes. Private and corporate aircraft owners, charter operators, flying schools, and agricultural and tour operators can all buy hull cover in Kenya. Hull is normally written on an agreed-value basis, so the sum insured is fixed at inception (usually from a recent valuation) and is not depreciated at total loss. Because local capacity is thin, the cover is typically fronted by a Kenyan insurer and reinsured through specialist Lloyd's aviation brokers.
How is an insurance bond different from a bank guarantee?
Functionally similar: both guarantee performance to a beneficiary. Practically, bank guarantees usually require 100% cash collateral; insurance bonds are issued against the principal's credit standing and a counter-indemnity, freeing up working capital. Premium replaces lock-up of cash.
What is PVT insurance in Kenya?
PVT stands for Political Violence and Terrorism insurance. It covers physical loss or damage to business assets, and the business interruption that follows, arising from terrorism, sabotage, riot, strike, civil commotion, and insurrection. It exists because standard Fire and IAR policies in Kenya exclude terrorism and sabotage, leaving that exposure uninsured unless a dedicated PVT policy is bought. It can be written stand-alone or as an add-on that sits alongside the IAR programme.
How much does cyber liability insurance cost in Kenya?
Cyber premiums are rated case by case, driven by annual revenue, industry sector, the volume of data held, IT security maturity (assessed by questionnaire and often an external scan of internet-facing assets), prior claims, and the limit chosen. Better security controls lower the premium, so businesses with multi-factor authentication, tested backups, and an incident-response plan pay less. Vike prepares clients for underwriting first, then arranges competing quotes, so we do not publish a single figure.

Ready to get the right cover?

Our advisors will compare quotes and find the best fit for you, at no extra cost.